 Baku 19° C
S&P to assess sufficiency of Azerbaijani bank’s client base for profitability of its ecosystem
- 04 July, 2024
- 15:08
Stay up to date with the top news!
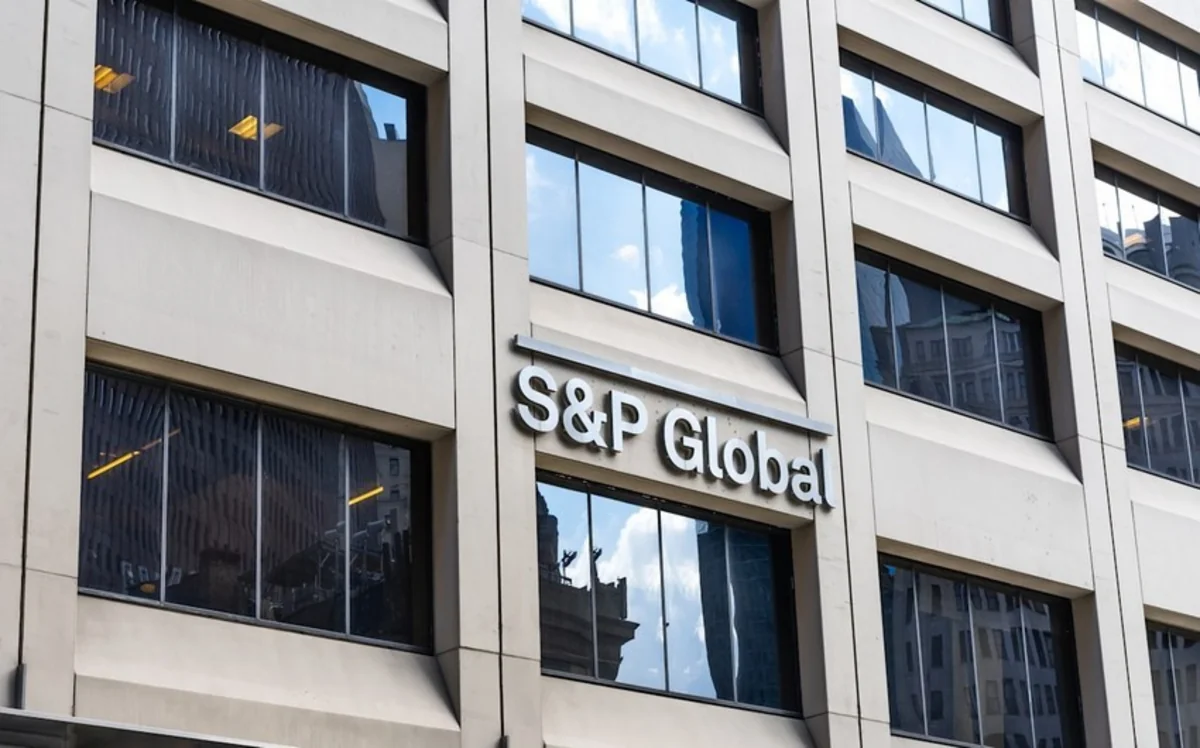
S&P Global Ratings has affirmed its 'BB-/B' long- and short-term issuer credit ratings on Kapital Bank, Report informs referring to the S&P.
The outlook on the long-term rating is positive.
"We believe Kapital Bank's nascent ecosystem can create an economic moat and help the bank retain its position as a leading retail bank in Azerbaijan. Kapital Bank's efforts to develop a payment business through PashaPay and a marketplace through Umico Market follow peers' successful implementations of similar ecosystems in Kazakhstan and Russia. The latter suggest that such ecosystems can strengthen banks' ties with customers, boost fee incomes, expand low-cost deposit bases, and create lending opportunities with small and midsize enterprises and individuals. That said, it remains to be seen if Kapital Bank's customer base is large enough to make this type of business model profitable. Similar ecosystems in the region operate in markets with significantly larger populations.
The development of the ecosystem has impaired Kapital Bank's profitability. Kapital Bank's return on assets (ROA) deteriorated to 3.4% in 2023 on a consolidated basis, from an average of 4.5% over 2018-2022. The decline resulted from an increase in expenses related to the development of the ecosystem, as well as the enhancement of the bank's and its subsidiaries' digital capacity. Kapital Bank's cost-to-income ratio deteriorated to about 54% in 2023, from 45% in 2022, and costs reached 5.5% of average assets. We expect the bank's performance will normalize at a healthy ROA of 2.5%-2.7% over 2024-2026," reads the report.
"We expect Kapital Bank will operate with lower capital buffers than in 2021 and 2022.Our risk-adjusted capital (RAC) ratio declined to 5.9% at year-end 2023 as Kapital Bank rapidly expanded its lending book. We expect the RAC ratio will remain at 5.25%-5.75% over 2024-2026, despite expectations of a slowdown in lending growth to 15%. This reflects our expectations that Kapital Bank will continue distributing 50% of its profits, while covering the regulatory capital gap with tier 2 subordinated instruments, which we consider have a low loss absorption capacity.
The positive outlook on Kapital Bank reflects our expectation that its efforts to develop an ecosystem can further entrench its already strong position in Azerbaijan's financial retail market over the next 12-18 months.
We could revise the outlook to stable if the bank's rapid growth puts material pressure on its capitalization and asset quality, or if it fails to maintain stronger-than-average returns.
We could raise the ratings if we consider Kapital Bank's new initiatives are value-accretive. This will require its ecosystem to reach at least breakeven point, with clear synergies between banking and non-banking businesses in place and a robust increase in customer loyalty. A positive rating action would also require that Kapital Bank's profitability metrics exceed those of peers, solid asset quality, and at least moderate capital buffers," the report says.
Author